Making sense of one’s dollars: Tips for maximizing financial resources
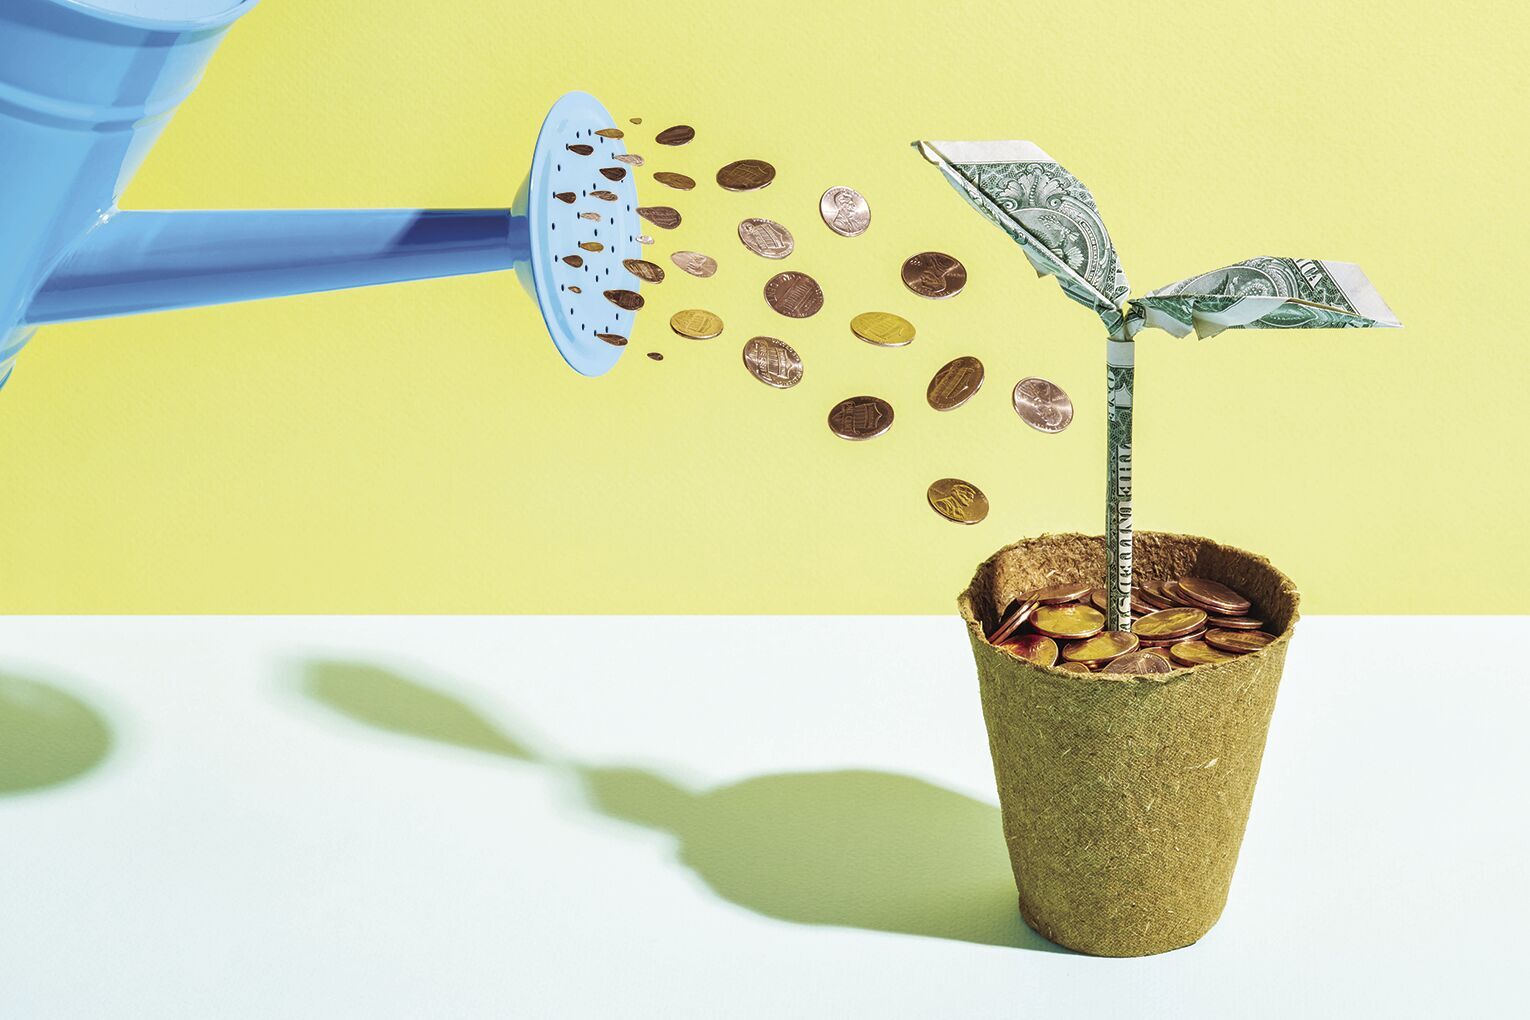
There is a quote often attributed to Albert Einstein, noted genius, about compounding interest. The verbiage changes a bit depending on who you ask, but it is said Einstein referred to compounding interest as “the most powerful force in the universe,” “eighth wonder of the world” or “mankind’s greatest invention.”
Whether the quote or attribution are completely accurate — it’s a source of internet debate — the sentiment about what compound interest can do for one’s finances is on point, according to Casey Nelson, a CPA and LPL financial planner.
“If you start young and you get that snowball rolling down the hill by starting to put dollars away, and you talk about a compounding rate of return on itself, 30 years later that annual return is a really significant number compared to that first year,” Nelson says.
Nelson has served as a financial advisor for KLN Family Brands for more than a decade, managing the company’s 401(k) and working on everything from a company level to questions from employees. His greatest advice to people is: Figure out early on how to live on 85% of your income, and save and invest the rest.
He acknowledges that can be easier said than done for people who don’t have a massive income and start out living on 100%, especially in a time of inflation.
“It’s hard to get dollars into the plan without squeezing yourself so hard you can’t live life,” Nelson says. “It’s a challenge, without a doubt, but if you can commit to living on 85% of what you make versus 100% — or like most of America, 110% and get themselves into debt — what an unbelievable feeling to just learn to live on 85%.
“It’s going to set you up for a tremendous amount of success.”
Of course, there is no universal advice, which is why Nelson says he is at KLN regularly to field questions from employees. Some people may want to start with putting 6% aside and work toward 15%.
“It’s different for everybody,” Nelson says. “The 72-year-old that’s going to work for another two years and wants to use the money they put in immediately to take it out at 74 is different than the 28-year-old who should be investing in stock and not worrying about ups and downs because they’ve got four decades before they’re going to touch it.”
But Nelson says the sooner people can learn to save and invest, the better. A lot of younger folks tend to put it off.
“I’ve had a lot of people come in 10 years later and say, ‘I wish I had done this 10 years ago,’” Nelson says. “I’ve never heard the person who’s been in the plan for 30 years say, ‘I really wish I wouldn’t have done that at 23 and [have] $500,000 in the plan.’
People need to recognize the significant differences between saving and investing, Nelson adds. Savings remain available in a pinch or for bigger expenses, but people should expect to let go of their money for some time with investments. The trick is investing without leaving oneself cash-strapped, he says.
“The biggest thing is finding a happy medium of chucking some dollars into savings, along with putting dollars into long-term investments,” he explains. “There’s a balance there, because you have to live life. It’s tough to strike that balance, but the people that do it young are, by far, the best off.”
Profit sharing and bonuses provide great opportunities for employees to boost their savings accounts while also treating themselves with something like a weekend trip.
“It’s important to have that in life,” Nelson says. “Not everything is all about saving constantly and worrying constantly. But there is something to be said for if you could take half of that check each time and chuck it into a savings account [and] do something fun with the rest. What a world of difference that would make to give you a little emergency cushion.”
Nelson would not necessarily advise changing 401(k) contributions because of a quarterly profit-sharing check, but a promotion or raise could be cause to re-examine those long-term investments. A raise is an ideal time to up the percentage of contributions to a plan because it won’t be as noticeable a hit on one’s pocketbook.
“I always tell people, if you get a raise and you learn to live on last year’s money, and you bump your 401(k) each year — and you can still live comfortably with a good mix of saving and investing — that’s when you’re going to have the most chance of success,” he says.
Nelson regularly cautions people about using credit cards. People often get into a bind when they think they can pay off something at introductory 0% rates but get caught 12 months later with 26% interest that can make it tough to get caught up. Don’t overextend on any debt, and save for the big purchases instead of purchasing them on credit, he advises.
“Credit cards can be great to build points, but if they’re not paid off monthly in full you should never use them,” he adds.
He encourages KLN employees to reach out to him if they have any financial questions.
“I’ve committed a lot of time to trying to be a good point of contact for anything financial, and I want it to remain that way,” Nelson says. “I’m here as a resource. It goes beyond just 401(k) I can talk to people about. If you’ve got a question, ask me.”
Securities and advisory services offered through LPL Financial, a registered investment advisor. Member FINRA/SIPC. KLN Family Brands is not affiliated with Casey Nelson and LPL Financial.